by Radu Magdin
For every euro Indonesia has invested in the European Union, the EU has invested more than twenty in Indonesia. At the end of 2023, European direct investment stock in the country stood at €25.1 billion, while Indonesia’s stock in the EU was €1.1 billion. That gap may tell us more about the next decade of EU–Indonesia relations than any tariff schedule. Indonesian capital has barely started to look at Europe. When it does, Central and Eastern Europe should be asking where it will land, and doing what it can to make sure part of the answer is here.
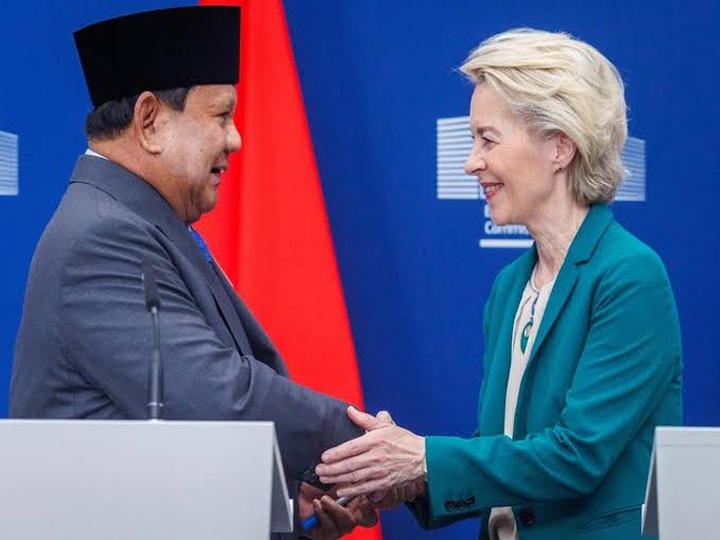
The moment is close. Brussels and Jakarta concluded the Comprehensive Economic Partnership Agreement in September 2025, together with an Investment Protection Agreement, after nine years of negotiations. The Commission sent both texts to the Council at the end of June. Signature is expected in the coming weeks, with entry into force targeted for 1 January 2027, once the European Parliament has given its consent and Indonesia’s parliament has ratified. Jakarta has its own reason to move quickly: its trade preferences under the EU’s Generalised Scheme of Preferences run out at the end of this year.
Why Indonesia matters
Indonesia is a market in its own right, much more than one more Southeast Asian destination. Its 283 million people make up more than 40% of ASEAN’s population, and it produces around 35% of the bloc’s GDP. It is a G20 economy of around $1.4 trillion, the world’s largest nickel producer and a fast-digitalising consumer society. With Indonesia Emas 2045 it has set itself the goal of becoming an advanced economy by the centenary of its independence. Its foreign policy, which it calls "free and active", gives it room to deal with every major power at once.
What the agreement opens
The EU and Indonesia traded €27.3 billion in goods in 2024 and €8.8 billion in services in 2023. The goods balance is lopsided: Europe exported €9.8 billion and imported €17.5 billion. CEPA removes duties on 98.5% of tariff lines. For European carmakers that have faced Indonesian duties of up to 50%, that is a real change in the market. The agreement also covers services, investment, digital trade, public procurement, intellectual property, energy and raw materials. Indonesia will allow full foreign ownership in telecommunications and computer services, which matters a great deal to CEE’s software and IT-services firms.
A confident region looking at familiar markets
Central and Eastern Europe enters this period with optimism. PwC’s latest CEO Survey found that 42% of CEE chief executives are very or extremely confident about revenue growth in 2026, against 30% globally. Almost half have started competing in new sectors over the past five years. Over a three-year horizon, however, CEE confidence falls to 39%, below the global 49%. Short-term optimism has not yet become a long-term growth strategy, and new geographies are one of the clearest ways to build one.
Our commercial footprint in Indonesia is still modest. Poland, the region’s largest economy, trades less than $2 billion a year with Indonesia, a figure Polish officials themselves consider too low. Romania’s bilateral trade doubled between 2022 and 2025 but reached only around $318 million, most of it Indonesian exports. CEE has only just begun to look at Southeast Asia.
The question of routes
CEPA is good news, and I want to say that clearly. My concern lies with what happens after the goods reach Europe.
Trade with Southeast Asia will grow. Within Europe, though, it is likely to follow the paths it already follows: into the large ports of north-western Europe, then eastwards by road and rail. Our Western European partners built that logistics architecture over decades, and they built it well. For most of CEE, however, it means the benefits of CEPA could arrive mainly as goods distributed from the West, rather than as trade the region originates, routes and controls itself. A few years ago, an estimate cited in the European Parliament put the container traffic bound for Central and Eastern Europe but passing through north-western European ports at around 5.5 million TEU a year. The direction of flow is West to East, and the margins follow the flow.
This is where CEE needs initiatives of its own, and the case reaches beyond Indonesia. The EU already has agreements with Singapore and Vietnam and is working on others across ASEAN. Each one will raise the same question about which European ports, corridors and distributors capture the value.
Constanța can be a large part of the answer, if it is developed and marketed seriously. It handles nearly all of Romania’s maritime cargo and is the EU’s main Black Sea gateway with regular container links to Asia. DP World has just doubled its container capacity there to around 1.5 million TEU and connected it by rail to western Romania. In May, Romanian freight forwarders signed an agreement to route Middle Corridor traffic through the port. Through the Danube and the rail network, Constanța reaches Hungary, Slovakia, Serbia and Czechia. The infrastructure is improving. The commercial story has yet to be told in Jakarta, Singapore and Ho Chi Minh City with the confidence Rotterdam brings to every negotiation. Selling a port is a policy task as much as an engineering one, and it calls for Romanian institutions to mobilise behind it.
Who controls the minerals?
A related question deserves attention. Indonesia is the world’s largest nickel producer and a major source of cobalt, and CEPA explicitly addresses energy and raw materials. CEE has the battery plants, automotive suppliers and electrical-equipment makers that will consume these materials.
Who will control their flow into Europe? Will it once again be the larger Western players that import and then distribute inside the single market? Or will individual CEE companies, and CEE states, be able to secure supply on their own terms? That question goes to the heart of Europe’s strategic autonomy debate, and it deserves a separate discussion. I intend to return to it.
Follow the families
There is another reason the CEE–Indonesia relationship deserves attention, and it lies in who owns the companies.
Indonesia’s economic history cannot be understood without its business families: Salim, Sinar Mas (the Widjajas), Djarum (the Hartonos) and Lippo (the Riadys), among others. They grew across generations, sectors and borders and came through the Asian financial crisis of 1997–98, some at great cost. The Salim group lost control of Bank Central Asia, which the Hartonos later acquired. Those families learned diversification, succession and regional expansion the hard way.
That ecosystem is maturing. PwC’s 2025 Indonesian Family Business Survey found that 27% of respondents already had a family office, most of them single-family offices, and that 43% of next-generation respondents saw resistance from the senior generation as an obstacle to transition. Indonesia is building the architecture of multigenerational capital and working through the tensions that come with it.
Central Europe’s business families are younger. Most were founded around or after 1989, and their founders took them through privatisation, EU accession, the financial crisis, the pandemic and now a period of geopolitical disruption. PwC estimates that family businesses account for 40–50% of private-sector jobs in CEE, and many are now in their first succession. Indonesian families bring experience of longevity and Asian scale. CEE families bring experience of fast transformation inside the single market. Each has something the other needs.
Family-to-family diplomacy
The next chapter of EU–Indonesia relations should therefore also be written family to family, alongside the Brussels–Jakarta and corporation-to-corporation channels.
I have in mind a structured CEE–Indonesia Family Business Corridor: twenty carefully selected families on each side, matched by sector. Agrifood would sit with agrifood, industrial manufacturing with industrial manufacturing, healthcare with healthcare, and consumer brands with families that own distribution. The right question for them is what they can build together. Sometimes the answer will be exports. Often it will be a joint venture, a minority stake, an acquisition, a manufacturing partnership or a co-investment vehicle. A CEE company entering Indonesia needs local distribution, capital, regulatory knowledge and relationships, and an Indonesian family entering Europe needs exactly the same.
Singapore can accelerate this. Southeast Asian families already use it for holding structures, financing and family-office functions. A working triangle is possible, with Indonesia providing scale, Singapore providing capital architecture and CEE providing European market access and industrial depth.
CEE as Indonesia’s European platform
The gateway works in both directions. For Indonesian companies, Central and Eastern Europe should be presented as a European platform in its own right, with manufacturing depth, engineering talent, competitive costs and access to both Western Europe and Europe’s eastern neighbourhood. Poland offers scale, Czechia and Slovakia dense manufacturing ecosystems, and Hungary long-standing Asian investment ties. Romania offers the Black Sea, Constanța and proximity to Ukraine’s reconstruction, while the Baltics bring advanced digital ecosystems.
Indonesia’s investment architecture makes this concrete. Danantara, the sovereign fund launched in 2025, gives Jakarta a single large vehicle for international deployment, and alongside it sit some of Asia’s most experienced private groups. CEE governments and businesses should be talking to both, and soon.
A corridor to build
CEPA will remove tariffs, protect investment and bring predictability. Ambition, however, will have to come from businesspeople and from the institutions willing to back them. The first eighteen months after entry into force will reward those who arrive prepared. That means a CEE–Indonesia CEO dialogue, sector missions measured by signed transactions, NextGen exchanges and co-investment structures. It also means a deliberate effort to route part of the new trade through Europe’s eastern ports.
I would like to see the first round of the family corridor convened in Bucharest within six months of entry into force, with Constanța on the agenda and Jakarta and Singapore at the table.
Central Europe and Southeast Asia have both spent much of their modern history being described as frontiers. CEPA gives them a chance to help each other move from frontier to intersection, from intersection to gateway, and from gateway to centrality.
 By: N. Peter Kramer